
5 Dubai Areas to Watch in 2027
Here are the best areas to invest in in Dubai in 2027
10/28/20267 min read

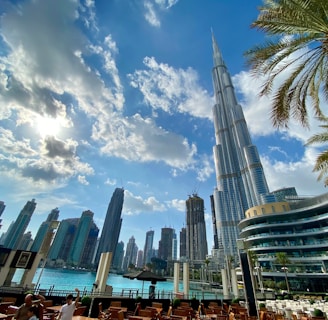
Dubai enters 2027 in a correction, not a boom. Home sales fell 38% by volume and 47% by value in Q3 2026, and S&P Global puts price declines at 5% to 15% between end-2025 and September 2026. In that market you buy infrastructure and scarcity, not momentum.
Each of these five areas has a concrete driver behind it. Entry runs from about AED 580,000 for a ready 1-bed in DLRC to AED 20M+ for a Palm Jebel Ali villa. All prices are DLD records via DXB Interact, pulled 28 October 2026, with price per sq ft recomputed from each sale. Yields are gross, before service charges and vacancy.
1. Dubai South
Why it works. Dubai South surrounds Al Maktoum International Airport. Dubai Airports plans to award Dh55 billion in contracts by end-2026, and phase one is due in 2032 with capacity for 150 million passengers a year. Jobs, and the people who rent homes near them, follow airports.
Price and transactions. Apartments trade at a median AED 1,660 per sq ft over the last 12 months. Sales reached 14,172 between January and 27 October 2026, against 7,783 in all of 2025. The main master projects are Emaar South, The Pulse, South Bay, Azizi Venice and Expo City Dubai.
Master projects and developers. Emaar South (Emaar, which DXB Interact rates at 99.2% delivery reliability), The Pulse and South Bay (Dubai South Properties), and Azizi Venice (Azizi), which leads sales by volume. Developer choice matters here: DXB Interact lists Azizi with 38 overdue projects and a median delay of 302 days.
Cons. 38,480 units are under construction across 127 projects, five times the 7,585 already delivered. Yields on villas and townhouses are modest, and resale prices have already come off their spring highs. The airport payoff is 2032, so you are early.
Who it suits. Investors with AED 600,000 to 2.5M and a five-year horizon or longer, who stick to developers with a clean delivery record.
2. Dubailand
Why it works. Dubailand is the cheapest route into a high-yield apartment with quick access to Al Khail Road and Emirates Road. Dubai Land Residence Complex (DLRC) trades at a median AED 1,410 per sq ft, up 8.7% year on year, with 6,381 sales in the last 12 months and an 8% gross yield.
The projects to watch. DLRC's top off-plan sellers over the last year are Samana Boulevard Heights (523 sales), Le Blanc Residence and Cove Grand Residence by Imtiaz, Peace Lagoons 2 by Peace Homes, Cybele and Seraph by Wadan, and Reef 998, selling at AED 1,270 to 1,670 per sq ft. Next door, Majan trades at AED 1,530 per sq ft (5,853 sales, 7% yield). At the premium end, Majid Al Futtaim's Ghaf Woods, in Wadi Al Safa 4 near Global Village, has sold almost every unit in its first Serra and Cilia towers since launching them in mid-2024, at around AED 1,750 to 1,780 per sq ft. First handovers are due in late 2027.
Ghaf Woods so far. Majid Al Futtaim sold 1-beds in Serra Tower 9 at about AED 1,222,000 (AED 1,774/sq ft) in December 2024. Comparable 1-beds there resold at AED 1,218,000 to 1,245,000 between October 2025 and July 2026, roughly flat, with one outlier at AED 1,380,000.
Cons. Wadi Al Safa 5, the area that contains DLRC, has 47 projects and 9,909 units due by end-2027, mostly studios and 1-beds. DLRC sales are down 17.6% year on year. Developer records vary widely: DXB Interact lists Samana with 9 of 17 projects overdue and Majid Al Futtaim with 4 of 9 overdue. Ghaf Woods resales show no premium over launch prices yet.
Who it suits. Yield-first investors with AED 400,000 to 1M in DLRC and Majan, and buyers who want a master-planned community from a large developer at Ghaf Woods. Buy ready for income now; buy off-plan only from a developer with a clean delivery record.
3. Al Yufrah 1
Why it works. Al Yufrah 1 is the new villa corridor off Al Ain Road. DLD records place Emaar's The Valley, Sobha Elwood and Sobha Sanctuary here. Sanctuary alone is a Dh50 billion, 37.5 million sq ft masterplan with about 20,000 homes and first handovers from Q3 2029.
Price and transactions. The area median rose from AED 721 per sq ft in 2021 to AED 1,369 in 2025 and AED 1,770 in 2026 so far. Over the last 12 months, The Valley's Vindera townhouses led with 392 sales at AED 1,752 per sq ft. Sanctuary villas sold at medians of AED 4.17M (The Greens) to AED 9.57M (The Grove), and Elwood villas at AED 11.64M, or AED 2,000 per sq ft.
Cons. Sales volume fell 45% in the last 12 months to 1,874. Of 11,626 units in the area, 9,255 are still off-plan, and Sanctuary plans 18,000 apartments on top. It is car-dependent and about 25 minutes from Downtown. Sanctuary's first phase gives few resale benchmarks yet.
Who it suits. End-users and family-villa investors with AED 2.5M to 12M and a five to seven year horizon.
4. Palm Jebel Ali
Why it works. This is Dubai's second Palm, and it is now being built rather than promised. Nakheel awarded Dh5 billion in 2024 for 723 villas on Fronds K to P and more than Dh3.5 billion in April 2026 for villas on Fronds A to F. First handovers start in phases from late 2026, and the masterplan includes more than 80 hotels and resorts.
Price and transactions. Villas trade at a median AED 3,450 per sq ft over the last 12 months, against AED 7,060 for villas on Palm Jumeirah. That gap of roughly half is the whole investment case. Sales rose 17% to 713 transactions. Nakheel's latest Beach and Coral Collection release on Frond F sold a 7,568 sq ft, 6-bed villa for AED 30.5M (AED 4,035/sq ft) on 26 Oct 2026.
The Palm Jumeirah comparison. Palm Jumeirah did grow into a global address, but not in a straight line. Its median fell from AED 2,116 per sq ft in 2015 to AED 1,223 in 2019 and only passed the 2015 level again in 2022. It stands at AED 3,547 in 2026. Patience paid there; short holds did not.
Cons. The entry ticket is AED 18M to 30M for a standard villa. There is no rental history yet, so yield is unknown. S&P expects the luxury and ultra-luxury segments to feel the biggest hit to investor sentiment in this correction.
Who it suits. High-net-worth buyers with a seven to ten year horizon who do not need rental income in the first years.
5. Dubai Creek Harbour
Why it works. Two catalysts are under way. Emaar's Dubai Square, a 2.6 million sq m retail, hospitality and commercial district anchored by a mall, is under construction with completion targeted about three years from December 2025. Emaar also said in January 2026 that the redesigned Dubai Creek Tower would go to tender within three months.
Price and transactions. Apartments trade at a median AED 2,560 per sq ft, up 6.3% year on year, with 3,980 sales in 12 months (up 12.5%) and a 7% gross yield. The median has risen 44% since 2021, from AED 1,774. Growth has slowed, though: 2.3% in 2025 and 4.8% so far in 2026. Emaar is the master developer, and DXB Interact rates its delivery record at 99.2%.
Is there more room to grow? Not from the discount alone. A 1-bed in Creek Harbour now averages AED 2,600 per sq ft, against AED 2,630 in Downtown. The gap has closed, so the next leg depends on Dubai Square and the tower actually delivering.
Cons. Prices have already re-rated, recent resales show softening, and the tower has no confirmed construction date. Emaar is still launching new towers here, such as Valia, which means continued new supply.
Who it suits. Buyers who want a ready Emaar apartment near the centre with AED 1.6M to 3M and a five-year horizon.
Bonus Area: Jumeirah Garden City
Why it works. Location. Jumeirah Garden City is a freehold district in Al Satwa that runs parallel to Sheikh Zayed Road, across from the Trade Centre district and the Museum of the Future, minutes from DIFC and Downtown. Satwa's reputation has kept prices below its neighbours, and the roads around it are being upgraded. The RTA converted the Al Satwa Roundabout into a signalised junction in October 2026, cutting peak waiting times and queues by up to 60%. Its April 2026 contract also includes a new bridge from Al Satwa Street to Sheikh Zayed Road and Financial Centre Street.
Price and transactions. Apartments trade at a median AED 2,150 per sq ft, up 10.3% year on year and up from AED 1,891 in 2024. There were 589 sales in the last 12 months, down 43%. The gross yield is 6%, with a median 1-bed rent of AED 85,000. Most of the stock is new: 2,093 of 2,694 units are still off-plan.
Developers. Plots here were sold to many private developers, so this is not a single-brand master community. Names include Enso, Vision Developments, Object One, Stamn and Jad Global, and several are new to the market. DXB Interact lists Object One with 7 of 9 projects overdue. Some are solid, and build quality in the delivered buildings I have seen is good, so choose the developer, not just the building.
Cons. Satwa's older streets still surround the new buildings, and the area's reputation takes time to change. Resale prices have not yet beaten developer prices in every building. Sales volume has fallen sharply this year.
Who it suits. Investors with AED 1M to 2M who want a central address that rents to people working in DIFC, Trade Centre and Downtown.
Risks that apply to all five
The correction is real. S&P expects a gradual price correction rather than a sharp fall. It expects apartment prices to fall more than villas and secondary sales to rise as investors offload. Past gains in the examples above do not repeat on schedule.
Gross is not net. Every yield here is before service charges, maintenance, agency fees and vacancy. On a 1-bed, those can take one to two points off.
Off-plan is a bet on the developer. Check the developer's delivery record, the escrow account and the handover date before the brochure.
Talk it through
The right area depends on your budget, your timeline and whether you need income now or growth later. I'm Ghadeer, Property Adviser. If you want the same-building numbers for a specific unit before you commit, contact me.
Sources
DXB Interact, DLD sale transactions, rent contracts, area and developer data, accessed 28 Oct 2026
Dubai home sale transactions fall in third quarter amid regional uncertainty, The National, 7 Oct 2026
Dubai to award Dh55bn in contracts by year-end for Al Maktoum Airport expansion, The National, 26 Aug 2026
Sobha launches Dh50 billion Sobha Sanctuary master development in Dubai, Gulf News, 26 Jan 2026
Dubai's Palm Jebel Ali villas head for first handovers this year, Nakheel, 16 Jun 2026
Emaar unveils Dubai Square, Emaar Properties, 5 Dec 2025
Emaar to relaunch Dubai Creek Tower with new design in three months, Construction Week Online, 14 Jan 2026
Dubai's Al Satwa Roundabout replacement to halve journey times, The National, 14 Oct 2026
RTA awards contract for Umm Suqeim, Al Wasl and Al Safa Streets Development Project, Government of Dubai Media Office, 26 Apr 2026
Ghadeer Samawi |
Your Guide to Dubai Real Estate through an expert lens
DXB BY GHADEER
contact@dxbbyghadeer.com
+971 52 713 5355
United Arab Emirates
© 2026 DXB by Ghadeer